The 2026 price list for a new home country
Italy charges €300,000 a year, Greece wants €800,000 for Athens or Mykonos, Uruguay now asks for real investment. What residency costs the very rich this year, and what changed.
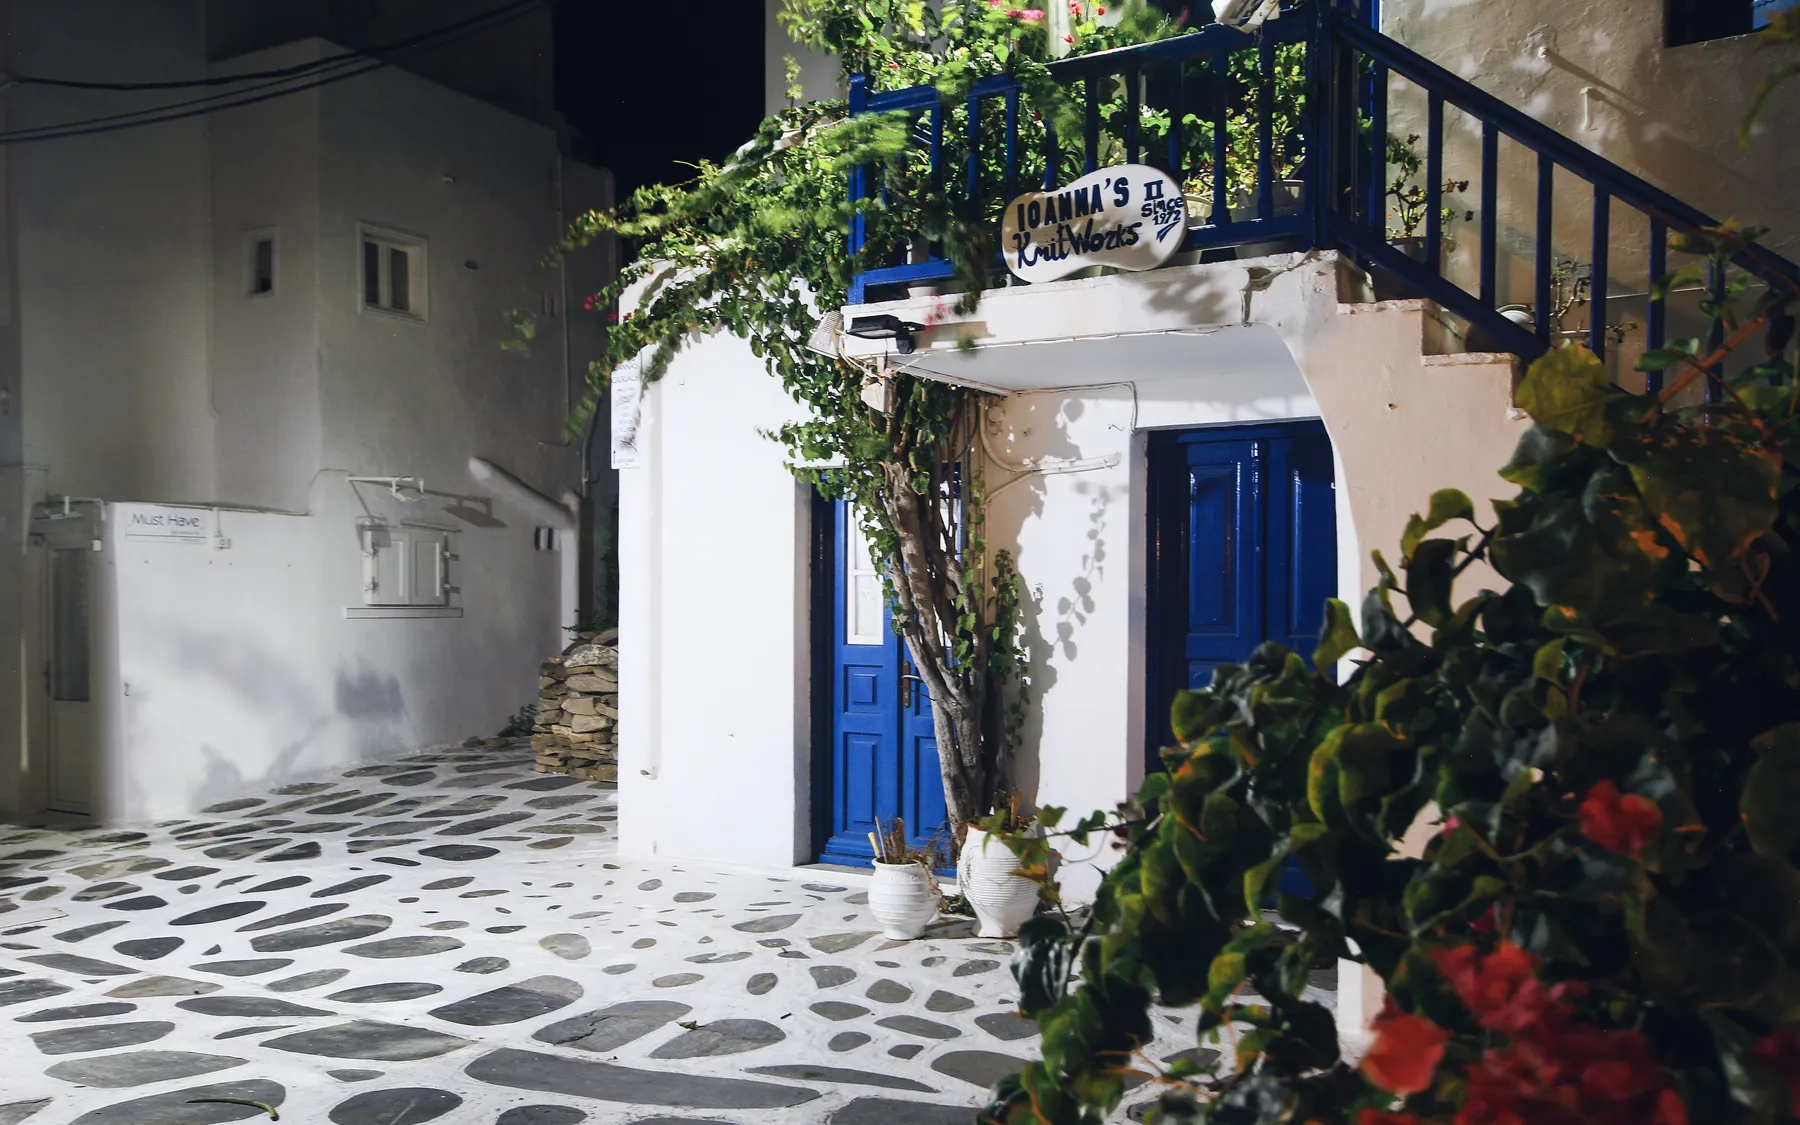
For the very rich, residence has become a product with a price list. Countries compete for wealthy newcomers with flat taxes, tax holidays and residence permits linked to investment. In 2026, most of them raised their prices.
Italy: €300,000 a year
Italy’s flat tax for new residents, introduced in 2017 at €100,000 a year on all foreign income, is the best-known offer in Europe. It was doubled to €200,000 in 2024 and raised again to €300,000 for newcomers from 2026. It still runs for up to 15 years, and family members can join for a smaller fixed sum.
The Catalan newspaper Ara reported that about 1,500 people used the scheme in 2023 and that it raised €315mn between 2020 and 2023. Milan, where most of them live, overtook Venice as Italy’s most expensive city in November 2025, at just over €5,000 a square metre.
Greece: €800,000 for the islands
Greece’s golden visa used to cost €250,000 anywhere in the country. It now has three prices. A property in Athens, Thessaloniki, Mykonos, Santorini or the other large islands must cost at least €800,000.
Elsewhere the threshold is €400,000, and converted commercial or heritage buildings qualify from €250,000. The larger tiers require at least 120 square metres of space.
Advisers report buyers moving to the Peloponnese and smaller islands to stay under the higher threshold.
Uruguay: no longer just an address
Uruguay has long been where wealthy Argentines went when they wanted a quiet life, a house in Punta del Este and no tax on their income from abroad. More than 2,300 foreigners received that exemption from the end of 2020, according to Bloomberg.
President Yamandú Orsi’s government has tightened it. Bloomberg reported that it wanted new residents to invest an additional $2mn in property. The budget law in force since 1 January ties the tax holiday to real economic investment in Uruguay, taxes some foreign rental income and gains, and requires the owners behind offshore structures to be identified.
Existing beneficiaries keep their terms.
Singapore: easier for family offices
Singapore went the other way on paperwork. From 15 June, family offices no longer need individual approval from the Monetary Authority of Singapore, and operate under a class exemption instead. The tax incentives still require at least S$20mn in assets under the 13O scheme or S$50mn under 13U, plus local investment professionals.
Singapore had about 2,000 single-family offices by 2025, up from around 400 in 2020.
The direction of travel
The pattern is consistent. Countries that attracted rich residents cheaply are now charging more, or asking for money spent locally, as populations complain about house prices and tax fairness. Britain abolished its non-dom regime in April 2025. Norway has closed exit-tax loopholes.
For the families moving, the bill is still small next to what they save. But the era of residence for the price of a flat and an address is ending. What replaces it is residence for the price of an annual subscription.
Sources
- Ara: Milan becomes the new refuge for billionaires from Dubai
- Greek golden visa thresholds, zone by zone (2026)
- Bloomberg via Yahoo Finanzas: Uruguay wants rich foreigners to pay more for tax exemptions
- Infocus: Uruguay tax residence in 2026, key changes for wealthy Argentines
- RSM Singapore: MAS updates tax incentive schemes for single-family offices
- Family office setup in Singapore: 13O, 13U and the 2026 class exemption
Cover image: Andreas Kakaris, Wikimedia Commons, CC BY-SA 4.0. Cropped.

More from OutBragger
View all OB / 01
The tax on a €10,000 hotel night: €24 in Barcelona, €3,350 in Amsterdam
Cities have raised tourist taxes to fight overcrowding. But most charge a flat fee per guest, which the richest visitors barely notice. Amsterdam, New York and now Edinburgh tax the room price instead.
 OB / 02
Switzerland’s club of rich foreigners taxed on their spending is shrinking, and paying more
The number of foreigners taxed on their living costs rather than their income has fallen by more than a third since 2012. The cantons that still offer the deal are collecting more than ever.
 OB / 03
Paramount’s new owners inherited a $400mn tax argument from Viacom
The IRS has proposed up to $400mn in extra tax on Viacom’s returns for 2017 to 2019. Paramount Skydance says it disagrees and will book any change in its third-quarter results.
Discussion
Join this article’s en edition thread. Replies in other language editions stay separate.